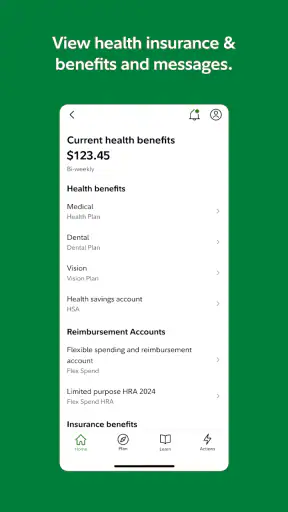
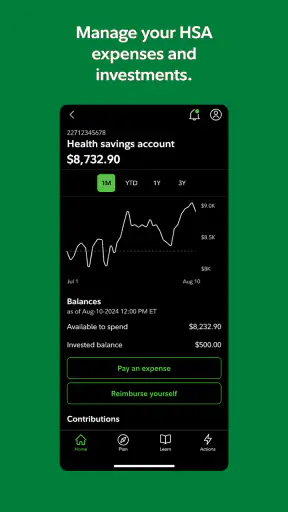
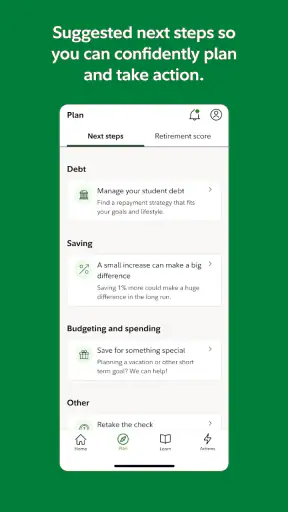
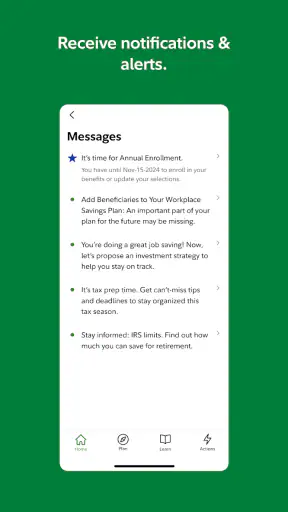
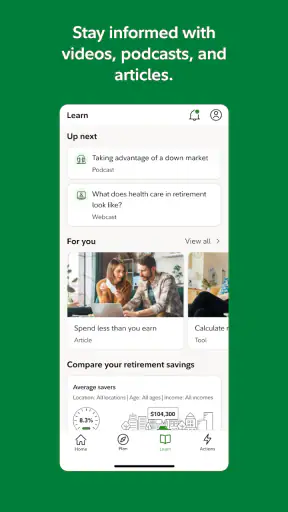
Managing a workplace retirement account is rarely exciting, but it is important enough that I want the process to be quick, clear, and dependable. NetBenefits - Fidelity is built for that narrow purpose: it gives Fidelity workplace account holders a mobile way to check and manage their benefits without relying on a desktop browser every time. After spending time with it, I see its strongest quality as convenience rather than entertainment. It earns attention during the first week because it puts account information close at hand, then earns its place over time only if you use it for small, repeatable money habits.
This is a free finance app from Fidelity Investments, with an Everyone age rating and support for devices running iOS 12 or later. It has been available since Apr 24, 2013, and the current version is 4.35.2. Its audience is fairly specific: people whose employers use Fidelity for workplace benefits. If that describes you, the app can become a practical part of your financial routine. If you are looking for a general budgeting tool, a stock-trading platform, or a complete personal-finance dashboard, I would look elsewhere.
What NetBenefits feels like after the first week
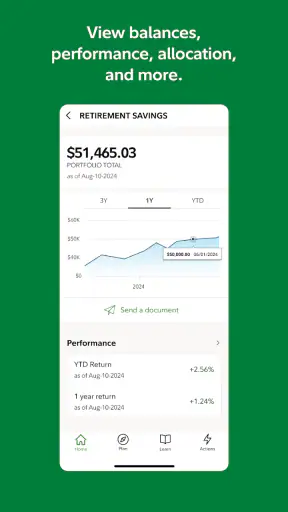
The first-week appeal comes from removing a familiar bit of friction. Instead of waiting until I am at a computer to think about a workplace account, I can open the app when a financial question occurs to me. That matters when I want to check whether a contribution went through, review the direction of my retirement savings, or simply remind myself that an old workplace benefit still exists.
I would not describe the experience as a replacement for learning about retirement planning. The app is a doorway into an account, not a personal adviser sitting beside you. Its value depends on the quality of the information you already have about your employer plan and on your willingness to interpret what you see. Still, having access in a familiar phone environment makes it easier to turn vague concern into a concrete check.
A realistic everyday example is changing jobs. During the first few weeks after leaving an employer, people often have several loose ends: final pay, benefits paperwork, and decisions about an old workplace account. An app like this is useful because it keeps that account visible while everything else is changing. I can check whether I still need to take action instead of allowing the account to disappear from my mental list.
Another useful moment is payday. I might open the app after noticing a change in my paycheck and compare that change with what I expect to be happening in my workplace savings. I would not use a quick phone check as the only basis for a major investment decision, but it can prompt me to investigate while the question is still fresh.
The app also benefits from being focused. Many personal-finance apps try to combine bank accounts, credit cards, spending categories, bills, investments, and credit monitoring. That can be helpful, but it can also bury workplace benefits under a large amount of unrelated information. NetBenefits - Fidelity keeps the center of attention on employer-linked accounts, which is exactly why it feels less distracting for its intended audience.
Its public reception suggests that it has reached a substantial audience: the app has more than a million installs, an average rating of 4.0, around twenty-five thousand ratings, and roughly seven thousand eight hundred written reviews. I treat those numbers as a sign of broad usefulness rather than a guarantee of a perfect experience. Finance apps are judged heavily by account access, employer configuration, and moments when users need information urgently, so individual experiences can vary.
The right way to test it early
During the first week, I would not judge the app only by how attractive the screens look. I would test whether it supports the few actions that matter to me. Can I reach the correct workplace account without confusion? Can I understand which balance or account area I am viewing? Can I find the information I need without repeatedly backing out and starting over?
I would also use the first week to establish a safe routine. Rather than opening it several times a day, I would choose a sensible check-in point, such as after a pay cycle or when reviewing monthly finances. This prevents the app from turning normal market movement into a source of unnecessary worry. A retirement account is designed for a longer horizon than a constantly refreshed phone screen.
One non-obvious advantage of this approach is that it separates two jobs that people often mix together. The app can help me verify that my workplace account is present and current, while a broader financial plan can handle budgeting, emergency savings, debt repayment, and household cash flow. Expecting one app to do all of those jobs is a quick way to become disappointed.
Why it can remain useful month after month
The lasting value is not in novelty. It comes from reducing the chance that a workplace account becomes forgotten. Retirement savings are easy to ignore because they are deducted before the money reaches a checking account. A mobile account view gives that invisible part of a paycheck a visible place in my routine.
For me, the best long-term use is periodic awareness rather than constant monitoring. A monthly review can answer practical questions: Is the account still connected to the employer relationship I expect? Does the overall direction of the balance make sense? Have I overlooked a decision that requires more careful attention? These checks are modest, but they can prevent years of complete inattention.
The app is also useful during life changes. A new job, a change in salary, a move, or a shift in household priorities can all be reasons to revisit workplace savings. NetBenefits gives me a convenient starting point for that review. It does not remove the need to read plan documents or understand the consequences of a decision, but it makes the account easier to include in the conversation.
That distinction is important. I would use the app to locate information and maintain awareness, not to treat a balance screen as a complete recommendation. Someone deciding how much to save, how to handle debt, or how to prepare for a near-term expense needs a broader view than a workplace account alone can provide.
Compared with a normal desktop website, the phone app wins when the task is short and unplanned. I can check an account while away from my desk, which makes small reviews more likely to happen. The desktop alternative may still be better when I want a larger view, more room for reading, or the calm concentration needed for a complex decision. I see the two formats as complementary rather than competing.
Compared with a general budgeting app, NetBenefits has a different strength. A budgeting app may show household spending more clearly, while this one is more directly tied to workplace benefits. Comparing them feature by feature misses the point. I would use a budgeting tool to understand where money goes and NetBenefits to keep an eye on the employer account that supports longer-term goals.
Compared with a broad investment app, NetBenefits is less appealing for someone who wants to explore many assets or actively manage a self-directed portfolio. Its appeal is the workplace connection. If my main purpose were researching investments across different providers, I would prefer a platform designed around that activity instead of trying to force this app into a role it was not built to fill.
Small habits that make the app more valuable
My first practical tip is to connect an app check with an event that already happens. A monthly household review, a pay-related task, or an annual benefits discussion is more reliable than promising myself that I will “check sometime.” The app becomes useful when it supports a habit, not when it becomes another icon I occasionally notice.
My second tip is to write down questions before opening the account. For example, I might want to confirm whether a contribution appears, identify which workplace account I am reviewing, or prepare a question for human support. This avoids wandering through financial information without a purpose and helps me recognize when I need more than a quick glance.
My third tip is to treat unusual changes as prompts for verification, not immediate conclusions. A number that looks different may deserve closer attention, but reacting impulsively to one phone session can create more harm than the original uncertainty. The app is most useful as an observation tool inside a thoughtful process.
A fourth insight is especially relevant for people with several employers over time: account visibility can help with organization, but visibility is not the same as consolidation or simplification. Seeing an older workplace account may remind me to review it, yet any decision to move or change it should be made after considering taxes, plan rules, investment choices, and personal circumstances. The convenience of the app should not rush that decision.
Maintenance is light, but attention still has a cost
The maintenance burden is lower than with a full budgeting system because I do not need to categorize every purchase or manually maintain a household ledger. That makes NetBenefits easier to keep in my routine. Once the app is installed and my account access works, the ongoing commitment can be limited to purposeful reviews.
However, “low maintenance” does not mean effortless. Workplace accounts can become complicated when employment changes, when a plan has several sections, or when the user is unsure which information matters. The app can present access to the account, but I still have to supply the judgment. If I open it without knowing what I am checking, the result may be more numbers and more questions rather than more clarity.
Security habits are part of the maintenance too. I would keep my phone protected, avoid treating a shared or unlocked device as a safe place for financial access, and take care when reviewing account details in public. Those are sensible habits for any finance app, but they matter more here because workplace accounts can represent years of savings.
I would also keep the app updated through the normal device process. The current release is version 4.35.2, and using a current version is a sensible way to avoid holding on to an outdated installation. That does not guarantee that every login or account screen will feel perfect, but it is better than assuming an old app build will remain ideal forever.
The app’s free price helps its long-term case. I do not have to justify another recurring subscription before deciding whether it belongs in my routine. That is a meaningful advantage over paid financial services, especially for someone who only needs occasional access to a workplace account.
Where the routine can become tiring
The main source of fatigue is repetition without a clear payoff. If I already know that my contributions are working and I have no decision to make, checking the same account too often can turn financial awareness into anxiety. The app cannot solve that problem by itself; the user has to choose an appropriate rhythm.
Another possible frustration is the gap between a simple question and a complicated answer. “What is happening with my workplace savings?” may lead to several account details that require context. A mobile screen is convenient, but it is not always the best environment for careful comparison or extended reading. When the issue is important, I would move to a larger screen or seek qualified guidance rather than forcing the phone session to do everything.
There is also a risk of confusing convenience with completeness. Because the app is dedicated to Fidelity workplace accounts, it may feel like a central financial home even when it is only one part of the picture. My checking balance, household spending, insurance, emergency fund, and other investments may live elsewhere. Anyone who wants a unified financial overview should expect to use another tool alongside it.
People who dislike account maintenance may find the app less satisfying than expected. It makes access easier, but it does not make financial decisions disappear. If I am unwilling to review plan information, understand my own goals, or follow up on a confusing item, the app becomes a passive display rather than a useful instrument.
I would also skip it as a primary tool if my employer does not use Fidelity for workplace benefits. The app’s focus is its strength, but that focus narrows its audience. A general finance app or the relevant provider’s own application would make more sense for someone without a Fidelity workplace relationship.
Does it deserve a permanent place on the phone?
My long-term verdict is positive, with a clear condition: NetBenefits - Fidelity earns lasting space when I have an active reason to manage or monitor Fidelity workplace accounts. It is not an app I would keep for entertainment or endless exploration. I would keep it because it turns an easy-to-forget part of my financial life into something I can reach when needed.
The app is best for employees who want convenient access to workplace savings, people moving between jobs, and anyone trying to build a calm monthly review habit. It is also useful for users who prefer a focused account tool instead of a broad financial dashboard filled with unrelated categories.
It is less suitable for a person seeking detailed household budgeting, extensive investment research, or a single screen covering every financial institution. In those cases, a budgeting platform, a broader investment service, or a desktop workflow may be the better choice. I would not install this app expecting it to replace those alternatives.
What I appreciate most is the balance between access and restraint. The app makes an important account easier to reach, but it does not need to become the center of my financial life. Used occasionally and with a specific question in mind, it supports awareness without demanding constant attention. Its recurring value comes from helping me remember and review, not from encouraging me to stare at retirement numbers every day.
Fidelity Investments has made a practical finance app for a specific audience, and that specificity works in its favor. The free cost, Everyone rating, long availability, and established user base make it an easy option to try when the workplace connection applies. I would recommend it to a friend in that situation, while reminding them that the app is a convenient account window, not a substitute for a complete financial plan.


